Most cheap travel policies exclude exactly what you will do in Peru. Spending time above 3,000 m (about 9,800 ft) and hiking for hours in the mountains are the two core activities on almost any southern Peru itinerary. They are also the two items that show up most often as exclusions in the fine print. The problem is that nobody reads that clause before paying. They read it after they need it. This guide explains what your insurance should cover, what policies usually leave out, and how to check it before you buy.
Is travel insurance required to enter Peru?
No. Peru does not require travel insurance as an immigration requirement for tourists, and nobody will ask for it at the entry checkpoint.
That leads a lot of people to skip it, and that is a math error. Private medical care in Peru is paid at the time of treatment, and a few days in a clinic in Cusco or Lima can cost several thousand dollars. Without a policy, that bill hits your credit card.
There is one case where it is mandatory in practice: many agencies require valid insurance before they will sell you a multi day trek, and the Inca Trail is the clearest example. The government does not require it. The operator does.
What a standard policy covers and what it does not
A standard travel policy covers three buckets: medical care for illness or accident, baggage issues, and flight disruptions.
What almost none of them cover by default are four things.
Activities above a certain altitude, which insurers set at 2,500, 3,000, or 4,500 m (about 8,200, 9,800, or 14,800 ft). Multi day treks or overnight hiking. Sports classified as adventure activities. And undeclared preexisting medical conditions.
All four apply in Peru. That is why a cheap basic policy rarely works for this destination without add ons.
Coverage you actually need for Peru
Having some insurance is not enough. For this destination, four specific coverages matter: real medical assistance, evacuation from the mountains, altitude above 3,000 m (about 9,800 ft), and, if you are trekking, an adventure or mountaineering rider.
Medical assistance and hospitalization
This is the core of the policy. It should cover doctor visits, tests, medication, hospitalization, and emergency surgery.
Check two things. First, that the limit is high enough, because $15,000 sounds large until you see what one night in intensive care costs. Second, that it includes emergency dental care, which is often listed separately with a low cap.
Also check whether the insurer works with private clinics in Cusco and Arequipa, or only in Lima. If your itinerary is in the highlands, a Lima only network does you little good.
Evacuation and medical transport
This is the coverage that costs the most when you need it, and the one few people review.
In Peru it can mean three different things. Coming down from altitude by road from a mountain trailhead, which is the most common. A helicopter transfer from a trek with no road access. Or medical repatriation to your home country if the case requires it.
A helicopter transfer from a mountain route can cost $5,000 to $15,000 depending on the area and conditions. If your itinerary includes long routes like Choquequirao or Ausangate, this coverage is not an extra. It is the main reason you buy the policy.
Confirm that the policy includes mountain rescue, not just medical transport from an urban clinic. Those are not the same thing.
Coverage above 3,000 m (about 9,800 ft)
Almost the entire classic southern Peru itinerary sits above that threshold. Cusco is at 3,399 m (11,152 ft), Puno at 3,827 m (12,556 ft), and several day trips easily pass 4,000 m (about 13,100 ft).
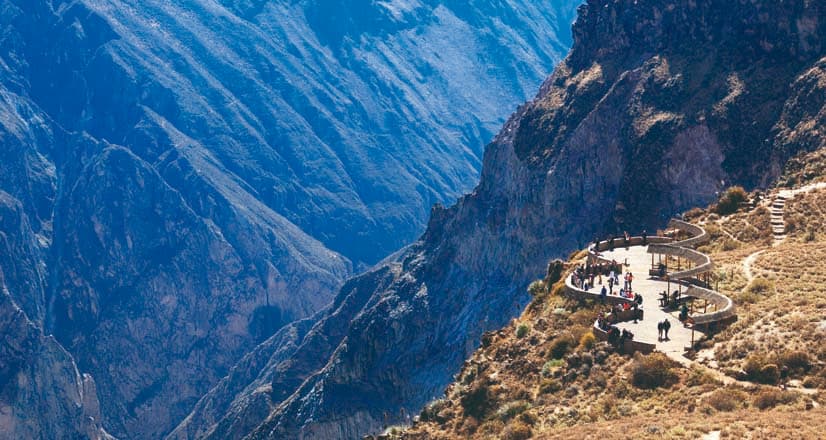
Humantay Lake is at 4,200 m (13,780 ft), and Rainbow Mountain tops 5,000 m (about 16,400 ft) at the main viewpoint. The Patapampa pass on the way to the Colca Canyon reaches 4,910 m (16,109 ft).
If your policy has an altitude cap below those numbers, half your trip is uncovered, and you will not find out until you file a claim.
Why so many policies exclude altitude
Because the actuarial risk changes. Acute mountain sickness and its severe forms can appear without warning, require immediate descent or evacuation, and generate high costs in a short time.
Insurers handle this in three ways. They set an altitude cap in the general conditions. They exclude altitude sickness as a specific diagnosis. Or they cover it only if you buy an extra mountain rider.
None of the three appears on the product homepage. All three are in the policy wording.
How to read that clause before you buy
Search the general conditions for the words altitude, elevation, mountain, mountaineering, and high altitude. They are usually in the exclusions section, not under covered benefits.
Pay attention to the difference between trekking and mountaineering. Many policies cover the first and exclude the second, then define mountaineering so broadly that an overnight hike falls under it.
If the wording never mentions altitude, do not assume you are covered. Email the insurer and ask for written confirmation before you pay. A reply in writing is worth more than a phone call.
Activities that usually fall outside a basic policy
A standard policy covers city tourism. What you do in the south, overnight treks, rafting, sandboarding, sometimes paragliding, usually sits in a different section. If you do not add it explicitly, it is not covered.
Multi day trekking
This is the critical point of travel insurance for Peru.
A one day hike usually falls under a standard policy. A multi day trek with overnight stays on the trail, no road access, and elevations above 4,000 m (about 13,100 ft) almost never does.
The Inca Trail and its requirements include this exact issue: the agency will ask for your policy, and many check that it covers the real altitude of the route. The same applies to Salkantay, Choquequirao, and the Ausangate circuit.
If your trip includes any of these, buy the adventure or mountain rider directly. The price difference is smaller than you think, and it is the only thing that makes the policy valid where you will actually need it.
Rafting, paragliding, and mountain biking
All three are offered in the Sacred Valley, and all three are classified as adventure sports in almost every policy wording.
Rafting is often covered up to a certain river grade. Paragliding and downhill mountain biking are left out of basic policies without exception.
If you plan to book any of these on the fly in Cusco, check first whether your insurance allows them. These are last minute decisions, and by then there is no time to add coverage.
Diving and water activities on the coast
If your itinerary includes Paracas, boat trips to the Ballestas Islands are fine under almost any policy.
Scuba diving is different. It is covered only with a specific rider and almost always with a depth limit. If you are certified and plan to dive, declare it.
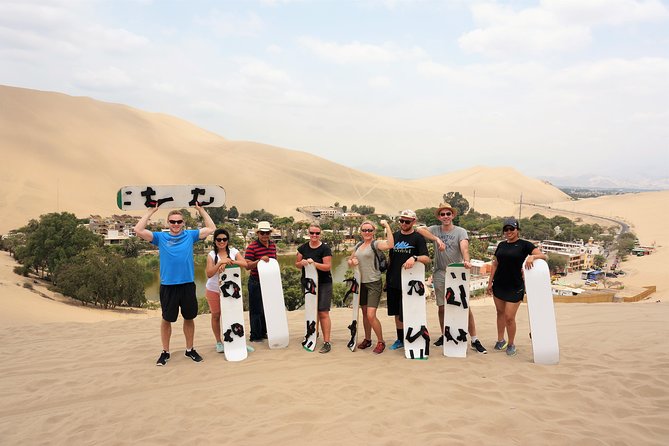
Sandboarding and dune buggies in Huacachina also show up as adventure activities in several policy documents, even though many travelers treat them as a casual tourist outing.
Reasonable minimum amounts in 2026
These ranges make sense for a trip through southern Peru. They are not the legal minimums of any particular market.
| Coverage | Reasonable minimum |
|---|---|
| Medical assistance for illness or accident | $100,000 USD |
| Evacuation and mountain rescue | $50,000 USD |
| Medical repatriation | Included with no sublimit |
| Emergency dental | $500 to $1,000 USD |
| Baggage | $1,000 to $1,500 USD |
| Trip cancellation | Full trip cost |
| Flight delay | $200 to $500 USD |
A $30,000 medical limit looks adequate on paper. It is not if you end up with a mountain evacuation plus several days in the hospital. That scenario burns through that amount easily.
Baggage, cancellation, and flight delays
These coverages do not replace medical protection, but they are what saves the itinerary when a flight is canceled or a train you booked months ahead falls through.
Cancel for any reason
Standard cancellation coverage only kicks in for listed reasons: serious illness, accident, death of an immediate family member, job loss.
Cancel for any reason coverage applies outside that list, but it reimburses a percentage of the trip, not the full amount, and you can only buy it in the first days after you purchase the trip.
It is worth it if you booked far in advance, which is exactly what Peru requires for the Inca Trail and trains to Machu Picchu.
What happens if your flight out of Cusco is canceled
Cusco’s airport shuts down for fog fairly often between December and March, and occasionally the rest of the year.
If that makes you miss an international flight out of Lima, the international airline does not always take responsibility, because they were technically two separate tickets. That is where your policy’s missed connection coverage comes in. It usually covers a new ticket or forced overnight lodging.
Check whether your policy requires a minimum connection time to trigger that coverage. Several require four hours or more. That overlaps with how southern Peru is connected and with the buffer you leave before your outbound flight.
Preexisting conditions and age limits
A preexisting condition is any diagnosis, treatment, or symptom from before you bought the policy. Asthma, hypertension, diabetes, heart disease, anemia.
The general rule is that standard policies do not cover them, although many include limited coverage for an acute flare up of a preexisting condition. That amount is usually low and does not cover ongoing treatment.
This matters in Peru because altitude can destabilize respiratory and cardiac conditions. If you have one, declare it even if the premium goes up. An undeclared preexisting condition is the number one reason claims get denied.
As for age, most products cover travelers up to 70 at a standard premium, ages 70 to 85 with a higher premium and reduced coverage, and anyone older with a specific product. If you are traveling to Peru with kids, minors are often included at no extra cost up to a certain age on family policies, but confirm that altitude coverage applies to them the same way.
How to use the insurance while you are in Peru
Owning the policy is not enough. If you call in the wrong order or fail to keep the paperwork, the claim can fail even when coverage exists.
Who you call first
Your insurer’s assistance hotline, not the clinic. That order matters.
Almost every policy requires prior contact to authorize care. If you go to a clinic on your own, pay, and then ask for reimbursement, the insurer can deny the claim for lack of prior authorization.
Save the assistance number on your phone and on paper. In mountain areas cell coverage fails, and paper still works when the phone does not.
What documents they will ask for
Policy number, passport, and a medical report with a diagnosis from the facility that treated you.
For reimbursement you also need the original invoice or receipt with a line item breakdown and proof of payment. Photograph everything as soon as you get it, before it gets crumpled in your backpack.
If there was a transfer, keep the medical transport receipt separate.
Reimbursement vs. direct payment
There are two models, and you should know which one you have.
With direct payment, the insurer pays the clinic and you do not front the money. It only works at facilities in the company’s network and requires prior authorization.
With reimbursement, you pay and claim later. The process takes weeks to months, and you need cash or available credit card limit at the time.
For Peru, prioritize a policy with direct payment and a clinic network in Cusco, Arequipa, and Lima.
Common mistakes when you buy
These are the failures that show up most often when someone files a claim and the policy does not respond.
- Buying the cheapest policy without opening the wording.
- Assuming trekking and mountaineering mean the same thing to the insurer.
- Not declaring a preexisting condition because you are afraid the premium will go up.
- Buying after you are already in the country or a few days before departure, which voids cancellation coverage.
- Relying on credit card insurance without checking the altitude cap.
- Keeping the assistance number only on your phone.
- Choosing a low medical limit because you are thinking about clinic visits, not hospitalization.
Checklist before you pay for the policy
Before you hit buy, confirm these eight points.
- The policy covers activities above the highest elevation on your itinerary.
- Acute mountain sickness is not listed as an exclusion.
- It includes mountain rescue, not only transport from an urban clinic.
- The adventure rider covers the specific treks you plan to do.
- Medical assistance is at least $100,000.
- It has direct payment and a clinic network outside Lima.
- You declared your preexisting conditions.
- You bought it before traveling and early enough to activate cancellation coverage.
If any item fails, you still have time to switch products. This step belongs right after you lock in flights, inside the full pre departure checklist.
Frequently asked questions
Does my credit card count as travel insurance?
Sometimes, with major limits. It usually requires that you pay for the ticket with that card, covers low amounts, and almost always excludes altitude and adventure sports. For a trip through southern Peru it is rarely enough. If you want to use it, request written proof of coverage and check the altitude cap before you decide.
What happens if I get sick on the Inca Trail?
The licensed agency activates its protocol and coordinates the descent, which depending on the point on the trail can be on foot, by horse, or by helicopter. Your insurance pays for that rescue only if you have active mountain coverage. Without it, you pay. That is why agencies ask for a policy before departure.
How much does travel insurance for Peru cost?
For two weeks, a suitable product with altitude and adventure coverage typically runs $60 to $150 depending on age, limits, and country of residence. The mountain rider usually adds $20 to $40. Compared with the total cost of the trip, it is a small fraction.
Can I buy it if I am already in the country?
Some companies allow it, but with a waiting period of several days and no cancellation coverage or coverage for issues that started earlier. You lose much of the product’s value. Buy it before you leave, ideally the same day you pay for the flights.
Does insurance cover altitude sickness?
It depends on the wording. Some policies cover it as a sudden illness, others exclude it outright, and others require a mountain rider. It is the first clause you should check for this destination. If the insurer will not confirm it in writing, look for another policy.